

JPay analysis by Appwee
JPay is a finance app from Jpay Mobile built around a very specific need: keeping in touch with people in correctional facilities while handling related payments. I found it more focused than a normal money-transfer app, because sending funds is only one part of the experience. Email-style messages, photos, and account management sit alongside the financial tools, so the app feels like a communication service with payment functions rather than a general-purpose banking app.
That focus is important when deciding whether it belongs on your phone. If you need to send money and messages to an incarcerated family member or friend, having those activities in one place can be practical. If you are simply looking for a low-cost way to transfer money to anyone, JPay is probably not the natural first choice. My overall impression is that its value depends less on how many features it has and more on whether your situation matches the service it was designed for.
What using JPay feels like in everyday life
The app is free to install, carries a Teen content rating, and has been available since October 15, 2012. Its current version is 26.4.0 and it requires Android 11 or newer. Those details matter because this is not a brand-new experiment: JPay has been around long enough to become familiar to a large audience, but compatibility still depends on having a relatively recent Android device.
JPay has an average rating of 3.9 from around 104 thousand ratings, with more than 36 thousand written reviews and over 5 million installs. I would read those figures as evidence of broad use, not as a guarantee that every transaction or message will feel smooth. Services involving payments and facility-specific communication naturally create stronger expectations than ordinary social apps. A delayed message or confusing payment step can matter a lot more when someone is waiting for contact.
The first thing I would do after installing it is clarify the exact recipient and facility details before trying to send anything. This is one of the less obvious practical points: a payment or message is not simply going to a regular email address or bank account. The destination matters, and entering information casually can create avoidable frustration. I would also keep the recipient’s identification details close at hand rather than relying on memory while moving through the app.
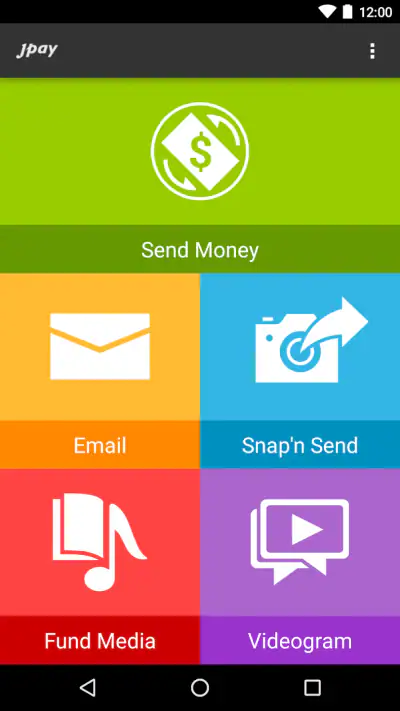
A realistic example would be a family member who wants to send a small amount of money and a short note before the weekend. With JPay, those tasks can be handled from the same service instead of switching between a general payment app, a separate messaging tool, and another method for photos. That concentration is the app’s strongest everyday advantage. It reduces the number of places a user has to remember, but it also means the app is only useful if the intended recipient and facility are supported by the service.
Why the communication side matters
The email function gives JPay a different feel from ordinary financial apps. A standard payment service usually treats a transfer as the entire job: choose a recipient, enter an amount, confirm, and wait. Here, the surrounding communication is part of the reason to use the app. A message can provide context for a payment, while a photo or written update can maintain a personal connection that a transaction receipt never could.
I would not treat the email feature as a replacement for every messaging platform. Its usefulness depends on the communication relationship and the rules connected to the recipient. The important distinction is that JPay is designed for a controlled communication environment, not an open social network. That can make the audience and purpose clearer, but it may also make the experience feel less immediate than consumer messaging apps people use with friends outside the correctional system.
Photos are another meaningful addition, especially for families who want to share ordinary moments that are difficult to describe in a short message. A useful habit is to prepare the message and review the attachment before submitting anything. In a service where communication may pass through specific controls, treating each submission as final is wiser than assuming you can casually edit or retract it later.
Trust begins with visible choices
For a finance and communication app, trust should come from what the interface lets me verify and control, not from a polished appearance. I pay attention to whether the recipient is clearly identified, whether the amount is visible before confirmation, and whether the app gives me a chance to review a message or photo before sending. These are small interface details, but they affect whether I feel in control of an important action.
I also prefer to separate browsing from committing. When I am checking a recipient, reading previous communication, or preparing a message, I want to know that I have not accidentally started a payment. With JPay, a careful user should slow down at every confirmation screen and read the destination and amount rather than tapping through automatically. That is especially important for anyone who is new to the service or helping an older relative use it.
The app’s free download is helpful, but “free” should not be confused with every possible activity being cost-free. A free app can still involve transaction-related charges or conditions connected to the service. Before confirming a payment, I would inspect the final review screen carefully and make sure the total is acceptable. This is a better habit than assuming the installation price tells me everything about the cost of using the service.
Another trust issue is account access. Because the app combines money and personal communication, I would use a unique password and avoid leaving the account signed in on a shared phone. I would also check the account area regularly so I know which recipient information is saved and which communication is associated with the account. These are practical precautions, not claims about a particular security system; they simply reduce the chance of sending something from the wrong profile or device.
Data-sensitive moments deserve extra attention
JPay handles information that is more personal than a typical shopping app: payment details, recipient information, written messages, and potentially private photographs. That combination changes how I use it. I would avoid composing sensitive details in a public place, double-check the recipient before attaching a photo, and keep the phone protected with the device’s own lock screen.
The photo feature deserves particular care. A picture can reveal more than the sender intended through its content, background, or the people visible in it. I would choose images deliberately and avoid sending documents, addresses, or other private material unless I am certain they are appropriate for the intended communication. The convenience of selecting a photo from the phone should not turn into careless sharing.
I would also think twice before using a shared family tablet or an old phone that other people can access. Even when an app has account controls, notifications or an open session can expose message activity. A private device is the better choice for JPay, and logging out when another person needs to use the phone is a simple step that protects both financial and personal information.
The same caution applies to payment preparation. I would not enter financial information while connected to an unfamiliar network, and I would verify that the app is the official JPay app from Jpay Mobile before signing in. These suggestions do not promise a specific level of protection; they are sensible ways to limit exposure when an app combines money with personal correspondence.
Where JPay has an advantage over ordinary alternatives
Compared with a normal bank transfer or peer-to-peer payment app, JPay is more relevant when the recipient is part of a correctional communication system. General payment apps may be excellent for sending money to a friend, splitting a bill, or paying a family member, but they are not built around facility-linked messages, photos, and related account workflows. Using one of those alternatives for this purpose may leave the communication side disconnected or unavailable.
Compared with ordinary email, JPay has a more direct connection to the financial and correctional context. Regular email is flexible and familiar, but it does not provide the same focused destination for this type of relationship. The trade-off is that JPay is less universal. I would not install it simply because I want another email inbox; I would use it because the recipient and situation make its specialized setup worthwhile.
There is also a practical emotional advantage to keeping a payment and a message together. A transfer without context can feel impersonal, while a note can explain why the money was sent or simply reassure the recipient. That does not make JPay a better banking tool, but it does make it more suitable for maintaining a structured connection where financial support and personal contact often overlap.
Who should use it, and who should choose something else
I think JPay is a good fit for family members, close friends, and support networks that regularly need to communicate with someone in a correctional facility and may also need to send money. It is especially useful for people who prefer one account for messages, photos, and payments rather than managing separate services. The focused design can save time once the recipient information is set up correctly.
I would be more cautious about recommending it to someone who only needs a conventional money transfer. A bank app or mainstream peer-to-peer service may be clearer for ordinary transfers between people who are not connected to JPay’s intended environment. Likewise, anyone who expects instant, unrestricted messaging should adjust their expectations before relying on the app for urgent communication.
It may also be a poor choice for a user with an older Android phone that cannot meet the Android 11 minimum requirement. In that situation, the issue is not preference but compatibility. Someone who shares a device with several people should think carefully as well, because the combination of financial activity and personal messages makes account separation more important than it would be in a simple news or entertainment app.
Small habits that make the experience safer and clearer
Before starting a payment, confirm the recipient’s identity and facility details instead of selecting the first similar name.
Review the amount and any displayed cost at the final confirmation stage, even if you have used the app before.
Write messages in a calm moment and inspect every attached photo before sending.
Use a private device, protect the account with a unique password, and avoid leaving the session open on shared hardware.
Keep payment records and communication decisions separate in your mind: a successful submission does not automatically mean the recipient has read a message or received funds immediately.
That last distinction is easy to overlook. Payment and communication may appear beside each other in the same app, but they serve different purposes and can have different stages of completion. I would save confirmation information when a transaction matters and avoid promising a recipient that money or a message has arrived until the app clearly shows the relevant status.
My cautious verdict after reviewing the app
JPay is not trying to be a universal finance platform, and I think it is better judged as a specialized bridge between financial support and personal communication. Its ability to send money, exchange email-style messages, and share photos gives it a clear purpose that ordinary banking and messaging alternatives do not combine in the same way.
My recommendation is positive for the right user, with an important condition: take your time with recipient selection, confirmation screens, photo sharing, and account access. The app’s usefulness is strongest when you already know why you need this particular service. It is weaker when you approach it expecting a general payment wallet or a completely open messaging app.
The 3.9 average suggests a mixed but substantial user experience, and I would interpret that fairly. JPay can be genuinely valuable in a situation where staying connected and providing financial help are closely linked, yet the same importance makes every unclear step feel more serious. I would install it on a compatible device, keep my account private, verify every payment before submitting it, and use the communication tools thoughtfully.
My bottom line: JPay is worth considering when its specialized correctional communication role matches your needs, but it should be used deliberately rather than casually. For that audience, the convenience of one focused service can outweigh its limitations. For everyone else, a conventional banking or messaging app will usually be the simpler and more natural choice.
Gallery
JPay Pros and Cons
- Conveniently sends money and support to participating inmates.
- Offers messaging and photo sharing where facility rules allow.
- Provides access to music
- games
- and other approved content.
- Lets users track transaction and message history in one place.
- Available on both Android and iOS for easier account access.
- Availability and features vary significantly by correctional facility.
- Service fees can make small payments relatively expensive.
- Messages and photos may require facility approval before delivery.
- Some transfers are delayed by weekends
- holidays
- or security checks.
- Account setup may require detailed inmate and facility information.
JPay Frequently Asked Questions
What is JPay used for?
JPay is a service designed to help people communicate with incarcerated individuals and manage related payments. Depending on the correctional facility, users may be able to send electronic messages, make deposits to an inmate’s account, purchase stamps, send money, or access other approved services. Available features are not identical everywhere, so checking facility eligibility before creating an account is important.
Can I use JPay to contact any inmate?
No. JPay access depends on whether the inmate’s correctional facility participates in the service and which features that facility allows. Before sending a message or payment, you generally need the person’s identification details and the correct institution. Facility rules, approval procedures, communication restrictions, and service availability can affect whether your transaction or message is accepted.
How do JPay messages work?
JPay messages are not always delivered like ordinary email or instant messages. Depending on the facility, messages may require electronic stamps, screening, approval, and sometimes a response from the incarcerated person. Attachments, photographs, and other media may also be restricted. Delivery times can vary, so users should review the facility’s communication rules and monitor the message status in the account.
Are JPay payments and deposits refundable?
Refund policies depend on the type of transaction, the correctional facility, and whether the payment has already been processed or credited. Fees may apply to deposits, messages, stamps, or other services, and some transactions may not be reversible once submitted. Carefully verify the recipient, identification number, facility, and amount before confirming any payment through JPay.
Is the JPay app free to download and safe to use?
The JPay app may be free to download, but many services inside it can involve transaction fees or paid messaging credits. As with any financial or communication application, download it only from the official Google Play Store or Apple App Store, use a strong password, and avoid sharing account details. Users should also review permissions, privacy information, and current pricing before using the service.














